Table of Contents
- Why Hiring Insured Contractors for Home Maintenance Matters
- Questions to Ask Home Service Providers
- Verifying Contractor Insurance Before Work Starts
- Frequently Asked Questions
Last Updated: September 28, 2026
Why Hiring Insured Contractors for Home Maintenance Matters
Hiring insured contractors for home maintenance means the company you let onto your roof or into your gutters carries coverage that protects you if something goes wrong. At Me And My Truck, we’ve been climbing ladders around Moscow and Pullman since 1987.
The risk isn’t the work. It’s who pays when a worker gets hurt on your property or a ladder lands on your neighbor’s fence. Without coverage, that bill can land on you.
So before you book anyone, ask one question: who’s covered if this goes sideways?
Insurance isn’t about the contractor’s peace of mind. It’s about yours. A policy in force means an injury or a dented gutter gets handled through a claim, not through your savings.
Questions to Ask Home Service Providers
Ask for the company’s legal name, insurance carrier, and policy details before work begins. If the answers get vague, slow down.
The questions worth asking, in order:
- What’s your full legal business name? You need it to verify anything else.
- Are you insured, and can you send proof? Ask for a certificate of insurance naming the coverage types and limits.
- Do you carry workers’ compensation? If a worker is hurt on your property and there’s no coverage, the problem can become yours.
- Who actually shows up? Employees or subcontractors? Subcontractors should carry their own coverage.
- Can I get this in writing? Scope, dates, and what’s included should be on paper.
These questions aren’t rude. Any provider who’s been around a while expects them.
Ask for the certificate before the crew is scheduled, not the morning they arrive. It gives you time to actually look at it instead of waving them up the ladder.
Verifying Contractor Insurance Before Work Starts
Verifying contractor insurance takes about ten minutes. You’re checking three things: the policy is real, it’s current, and it covers the work being done.
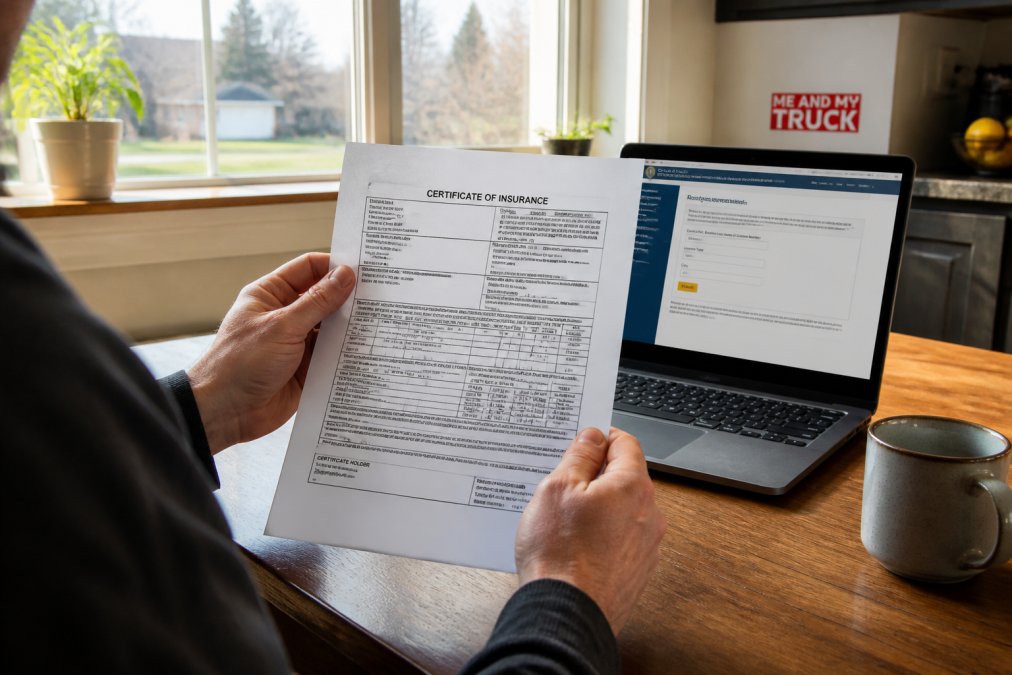
Here’s what to look at on the document:
- Named insured. Does it match the legal business name you were given?
- Policy dates. Coverage that lapsed last month doesn’t help you today.
- Coverage types. General liability handles property damage and injuries to others. Workers’ compensation handles injured workers.
- Limits. A policy with very low limits may not cover a serious incident.
- Certificate holder. Ask to be listed, so you’re notified if the policy is cancelled.
Then do the part almost nobody does: call the carrier’s number on the certificate and confirm the policy is active.
Skipping verification because the crew seems friendly and the schedule is tight is how homeowners end up absorbing a medical bill or a property damage claim. The ten minutes you spend now is the cheapest protection available.
| What to Check | Where to Look | Why It Matters |
|---|---|---|
| Legal business name | Certificate of insurance | Confirms the policy belongs to who you hired |
| Policy dates | Certificate of insurance | Expired coverage protects no one |
| General liability | Certificate of insurance | Covers property damage and injuries to others |
| Workers’ compensation | Certificate of insurance | Covers injured workers on your property |
| Active status | Call the carrier directly | Confirms the certificate is genuine and current |
If you hire someone uninsured and they damage your property, you may end up filing a claim on your own homeowner’s policy. That’s a headache nobody wants over a gutter cleaning.
At Me And My Truck, we handle gutter cleaning, window cleaning, roof moss treatment, junk removal, and local moving around the Palouse, and we’re happy to show proof of coverage before we start. Call or text (208) 882-5641, or send a photo of the job for a free quote. Every job is different, so we’ll talk through yours before we give you a number.
Frequently Asked Questions
What are red flags when hiring a contractor?
Watch for anyone who won’t provide a written contract, can’t produce a certificate of insurance, asks for full payment upfront, or pressures you to skip a written estimate. A contractor who avoids questions about their professional credentials or refuses to share their legal name is a risk. High demand and labor shortages have driven some homeowners to skip due diligence, so slow down and verify before any work begins.
What are the risks of hiring someone without insurance?
If an uninsured worker gets hurt on your property, you could be responsible for their medical bills. If they damage your home, you may have no way to recover the loss. Hiring insured contractors means their general liability insurance covers property damage and their workers’ compensation covers injuries. Without proof of coverage, you carry the financial risk for someone else’s accident.
How can I verify a contractor’s insurance status?
Ask for a certificate of insurance and call the phone number listed on it to confirm the policy is active. Check that the legal name on the COI matches the name on your written contract. For licensed trades, look up the contractor on your state regulatory board’s website. This verification process takes a few minutes and protects you from headaches later.
The hardest part of hiring help isn’t finding someone willing to do the work. It’s finding someone who’ll still be around, and covered, if something goes wrong. Me And My Truck has taken care of Palouse homes and businesses since 1987, and we’re glad to walk you through our coverage, our process, and what your job actually needs before we start. Get started with Me And My Truck and cross one more thing off your list.